Introduction
In our last few lessons, we've forged the essential components of a Discounted Cash Flow (DCF) valuation. First, we calculated the Free Cash Flow to the Firm (FCFF), which represents the raw, unlevered cash a business generates. Then, we determined the Weighted Average Cost of Capital (WACC), the risk-adjusted rate required to translate those future cash flows into today's value.
Now, we assemble the machine. This lesson integrates these parts to build a complete, two-stage DCF model. We will walk through the entire process: projecting cash flows through a high-growth phase, estimating the company's value in a stable future (its terminal value), discounting everything back to the present, and finally, translating the total enterprise value into an intrinsic value per share.
This is the core of intrinsic valuation. For an operator, a DCF is not a theoretical exercise; it's a dynamic framework for converting your views on a company's growth, profitability, and risk into a concrete number. Our goal is to master the mechanics so we can focus on what truly matters: the quality of our assumptions.
The Architecture of a Two-Stage DCF
A company's life, for valuation purposes, can be split into two distinct periods. A two-stage DCF model reflects this reality.
-
The Explicit Forecast Period (Stage 1): This is a high-growth phase, typically lasting 5 to 10 years. During this time, we have some degree of visibility into the company's prospects, allowing us to build a detailed, year-by-year forecast of its free cash flows. For a young, fast-growing company, this period might be longer; for a mature business, it could be shorter.
-
The Terminal Period (Stage 2): Beyond the explicit forecast, it's impossible to predict year-by-year performance. Instead, we assume the company matures and settles into a stable state, growing at a constant, perpetual rate. We capture the entire value of the company from this point to infinity in a single number: the Terminal Value.
The diagram below from Professor Damodaran's notes illustrates this structure perfectly.
[PDF] Lecture Note Packet 1 Intrinsic Valuation - NYU Stern
This diagram shows the fundamental structure of a DCF valuation. Cash flows are projected for a high-growth period (CF1 to CFn), followed by a terminal value representing all future cash flows. Both components are discounted back to the present to arrive at the company's value.
Building the Model: A Practical Walkthrough
Theory is one thing; execution is another. The best way to understand the DCF process is to build one. The following video provides an excellent step-by-step guide to constructing a full DCF model in Excel. It covers every stage, from projecting cash flows to arriving at an implied share price.
Build A Full Discounted Cash Flow Model for a REAL Company
This video from Kenji Explains is a complete, hands-on tutorial for building a DCF model for a real company. It's an ideal resource for seeing how all the pieces we've discussed fit together in practice.
Watch the entire video. It is structured around the core steps we are covering: Projecting Free Cash Flows: This section demonstrates how to forecast the line items needed to calculate FCFF for the explicit period. This is a practical application of what we learned in Lesson 20. Calculating the Discount Rate (WACC): This part covers the WACC calculation, which we tackled in our previous lesson. Notice how the calculated WACC is then used as the discount rate for the cash flows. Calculating Terminal Value and Enterprise Value: Pay close attention here. This segment shows how to calculate the terminal value using the perpetuity growth method, discount it and the projected cash flows, and sum them to get the Enterprise Value. Calculating the Implied Share Price: This final part demonstrates the crucial "bridge" from Enterprise Value to Equity Value and then to the implied price per share.
Let's now break down the most critical and assumption-driven parts of this process: calculating Terminal Value and bridging to Equity Value.
Terminal Value: The Engine of the DCF
In most DCF models, the Terminal Value (TV) can account for 70% or more of the total Enterprise Value. This makes the assumptions behind it incredibly important. An analyst who gets the TV wrong gets the valuation wrong. There are two primary methods for calculating it, and a smart analyst uses both to cross-check their work.
1. Perpetuity Growth Method (Gordon Growth Model)
This method assumes the company's free cash flows will grow at a constant, stable rate (g) forever, starting the year after the explicit forecast period ends.
The formula is:
- is the free cash flow in the last year of your explicit forecast.
gis the perpetual growth rate.WACCis your weighted average cost of capital.
The most critical assumption here is g. It cannot be higher than the long-term growth rate of the economy in which the company operates (e.g., nominal GDP growth). If a company grew faster than the economy forever, it would eventually become the economy. A reasonable g is often in the 2-3% range for a developed market.
2. Exit Multiple Method
This method assumes you sell the business at the end of the forecast period for a certain multiple of a financial metric, typically EBITDA.
The formula is:
- is the EBITDA in the last year of your explicit forecast.
- The
Exit Multipleis usually based on the current trading multiples of comparable public companies.
The Analyst's Sanity Check
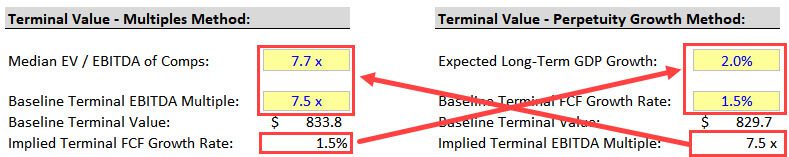
Relying on only one method is a rookie mistake. A professional analyst calculates TV using both methods as a sanity check. You can derive an implied growth rate from an exit multiple, and an implied exit multiple from a growth rate. If the implied growth rate from your chosen exit multiple is 8%, you know something is wrong. Likewise, if your perpetuity growth assumption implies an EV/EBITDA multiple of 30x for a stable, mature company, your g is likely too high.
From Enterprise Value to Equity Value Per Share
After discounting all the projected FCFFs and the Terminal Value and summing them up, you arrive at the Implied Enterprise Value (EV). This is the value of the company's core business operations attributable to all capital providers (debt and equity holders).
However, as a stock market investor, you care about the value belonging only to the common shareholders. To get there, we must cross the "bridge" from Enterprise Value to Equity Value.

The calculation is as follows:
Equity Value = Enterprise Value - Total Debt - Preferred Stock - Non-controlling Interests + Cash and Cash Equivalents
Let's quickly review the logic for these adjustments.
IB Interview Guide, Module 4: Equity Value, Enterprise ...
This guide from Breaking Into Wall Street provides a very clear, practical explanation of the bridge between Equity Value and Enterprise Value.
Read the section titled "How to Calculate Current Enterprise Value". Focus on understanding why you subtract non-operating assets like cash and add liabilities like Debt and Noncontrolling Interests. The text clearly explains the rationale for each adjustment.
Once you have the Implied Equity Value, the final step is simple:
Implied Share Price = Implied Equity Value / Fully Diluted Shares Outstanding
This gives you the intrinsic value per share according to your DCF model, which you can then compare to the current market price.
The Complete Picture: A Professional Example
To see how all these components come together in a professional format, look at this one-page DCF summary for Heineken from Professor Damodaran.
[PDF] Lecture Note Packet 1 Intrinsic Valuation - NYU Stern
This is a real-world, expert-level DCF summary. It condenses the entire valuation onto a single, information-dense page.
Study the Heineken valuation table. Trace the logic from top to bottom: Assumptions are clearly laid out (growth, margins, reinvestment). FCFF Forecast (the row labeled FCFF) is calculated for each of the 10 years in the explicit period. Terminal Value is calculated using a perpetual growth rate of -0.5% (reflecting a mature, perhaps declining, market) and a terminal cost of capital. Discounting brings the PV of the 10-year cash flows and the PV of the terminal value to the present. The Bridge at the bottom sums the present values to get the Value of operating assets, then subtracts debt and minority interests to arrive at the value of equity, and finally the value per share.
This example encapsulates the entire process we've learned today, demonstrating how assumptions flow through the model to produce a final valuation.
Conclusion
You have now built a complete Discounted Cash Flow model, the cornerstone of intrinsic valuation. This tool, when used with discipline, allows you to look past market narratives and develop your own independent assessment of a company's worth.
Key Takeaways:
- A DCF model is built in two stages: an explicit forecast period of high growth and a terminal period of stable growth.
- Terminal Value is a critical, highly sensitive component. You must use both the Perpetuity Growth and Exit Multiple methods as a sanity check on your assumptions.
- The DCF directly calculates a company's Implied Enterprise Value. You must "bridge" this to Implied Equity Value by adjusting for cash, debt, and other non-equity claims.
- The final output—the implied share price—is only as good as the assumptions you feed into the model. The model's real power lies in its ability to test these assumptions.
In our next lesson, we will explore Multiples Valuation. While DCF tells us what a company should be worth based on its fundamentals (intrinsic value), multiples tell us what the market is willing to pay for similar companies right now (relative value). Comparing these two perspectives is essential for identifying true market mispricings.