Introduction
In our previous lesson, we established the fundamental principle that the valuation of liabilities is always purpose-driven. We explored why different stakeholders—such as investors, regulators, and management—require different views of a company's financial position, leading to the use of multiple valuation bases.
Now, we will build directly on that foundation by moving from the "why" to the "how." This lesson will compare and contrast the key features of these different valuation bases. You will learn to distinguish between traditional, statutory, and the more modern market-consistent and realistic approaches that are central to current actuarial practice. Our goal is to deconstruct these methods so you can clearly articulate their underlying principles, assumptions, and practical implications.
From Traditional Methods to Market Reality
Historically, a common approach to valuation was the traditional discounted cashflow method. As you know from your prior studies, this involves projecting future cash flows and discounting them to the present. The key feature of the traditional actuarial approach, however, was its use of long-term, smoothed assumptions for both assets and liabilities, often disconnected from their current market values.
To understand this baseline approach and the shift away from it, let's turn to a core text from the Actuarial Education Company (ActEd).
[PDF] Subject CP1 - CMP Upgrade 2021/22 - Actuarial Education
This chapter from the ActEd study material provides a clear breakdown of different valuation methods.
First, read the introduction in Section 1.1, from the beginning. This sets the stage by introducing the main valuation types. Next, focus on Section 1.3, "Traditional discounted cashflow method". Pay close attention to the description of how both assets and liabilities are valued using long-term assumptions and the central criticism of this method: the divergence of the asset valuation from its market value.
The key takeaway is that the traditional method prioritizes stability. By using long-term discount rates and a smoothed valuation of assets, it avoids the volatility inherent in market fluctuations. However, this stability comes at the cost of realism. An asset's "value" under this method might be significantly different from the price you could actually sell it for, creating a potential disconnect from the firm's true financial position.
This disconnect is particularly relevant when considering statutory valuation bases. A statutory basis is one that is prescribed by law or regulation. While modern statutory bases (like Solvency II) are often market-consistent, many older or specific-purpose statutory rules can be more procedural and less reflective of economic reality.
Consider the following example from the Illinois Teachers' Retirement System. It starkly illustrates how a "Statutory Funding Plan" can produce a required contribution that is dramatically different from an "Actuarially Determined Contribution" which is based on a more realistic funding policy.
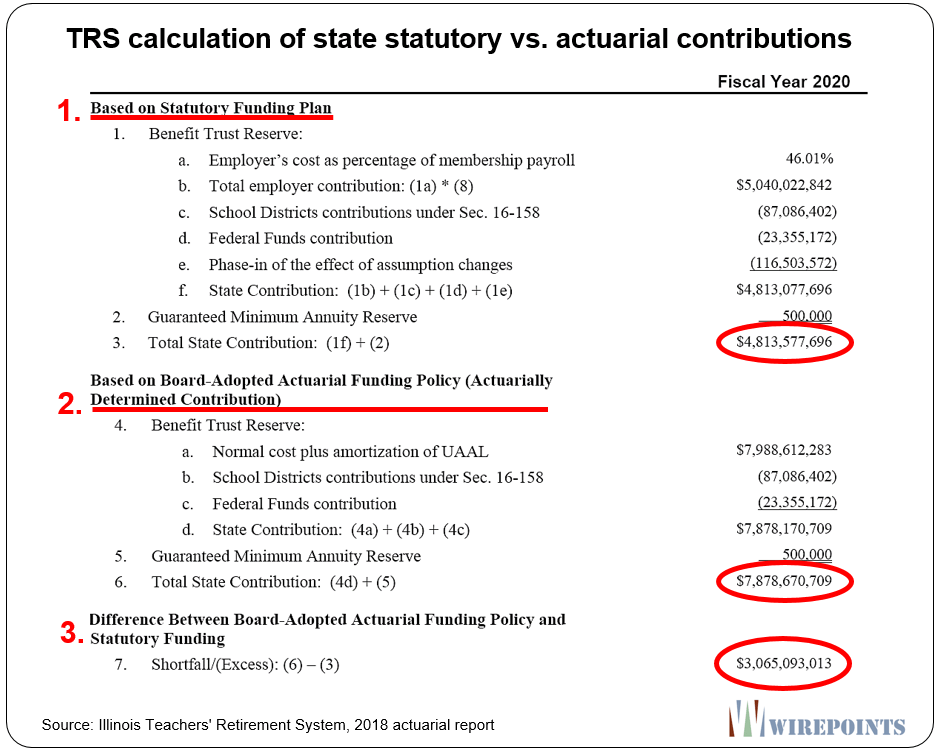
This shows that a statutory basis is not inherently "right" or "wrong"; it is simply a set of rules to be followed for a specific purpose, and its economic implications must be understood.
The Rise of Market-Consistent Valuation
The limitations of traditional methods and the potential for statutory rules to diverge from economic reality led to a global shift towards market-consistent valuation. This philosophy underpins most modern regulatory and accounting standards, including Solvency II in Europe.
The core idea is to align the valuation of assets and liabilities with observable market prices, providing a more objective and realistic snapshot of a company's financial health.
Solvency II - Simply Explained in 3 Minutes
This short video from In 3 Minutes provides a concise overview of the Solvency II framework.
Watch the clip from pillar one to understand that calculating capital reserves and liabilities is a core pillar of this regulation. Then, jump to the end, from the concluding remarks, where the video explicitly states that Solvency II uses market-consistent valuation models.
So, what does it mean for a valuation to be "market-consistent"? It means that the value of the liabilities should be consistent with the value of the assets that replicate their cash flows. This principle seeks to eliminate arbitrage opportunities between the valuation of assets and liabilities. The ActEd text you reviewed earlier introduces the two primary ways to achieve this.
[PDF] Subject CP1 - CMP Upgrade 2021/22 - Actuarial Education
Let's return to the ActEd text to define the methods for achieving a fair, market-consistent value.
Please read Section 1.5, "Fair valuation". Focus on the two definitions of fair value and the two main approaches for estimating it: the Replicating Portfolio approach and the Risk-neutral market-consistent approach.
Let's break down these two powerful concepts:
-
Replicating Portfolio Approach: The value of a liability is defined as the market value of a portfolio of traded assets that would generate cash flows to match the liability's expected payments. The logic follows the principle of no-arbitrage: if you could create a portfolio of assets for price that perfectly pays off a liability, then the "fair value" of that liability must be .
-
Risk-Neutral Market-Consistent Approach: This is likely familiar from your CM2 studies. It involves two steps:
- Projecting the expected liability cash flows on a best-estimate basis. From your background in probability theory, you can understand "best estimate" as the probability-weighted average of all possible outcomes, with no deliberate prudence.
- Discounting these best-estimate cash flows using a risk-free rate of interest. The term structure of risk-free rates is derived from the market (e.g., from government bonds or interest rate swaps).
This approach is conceptually equivalent to valuing the liabilities in a hypothetical "risk-neutral world" where all assets are expected to earn the risk-free rate.
Realistic vs. Market-Consistent
In practice, particularly in a regulatory context, you will often hear the term "realistic" valuation. This is closely related to, and often built upon, market-consistent principles. A realistic valuation aims to be a comprehensive measure of the economic value of liabilities, taking into account all factors.
A market-consistent valuation is the core component of a realistic balance sheet. It provides the value of the expected cash flows. However, a full realistic valuation under a regime like Solvency II goes further.

As the diagram shows, the total liability, or Technical Provision, is the sum of:
- Best Estimate Liability (BEL): The probability-weighted average of future cash flows, discounted using the relevant risk-free interest rate curve. This is the pure market-consistent value.
- Risk Margin (RM): An additional amount on top of the BEL. It represents the theoretical compensation a third party would require to take on the non-hedgeable risks associated with the liabilities (e.g., mortality, expense, and operational risks).
For the purpose of this lesson, the key point is that the BEL is the cornerstone derived from market-consistent valuation principles. The full "realistic" liability under a regulatory framework includes additions like the Risk Margin.
[PDF] Valuation of Life Insurance Liabilities on a Market-Consistent Basis
This paper from the Society of Actuaries provides excellent background on the regulatory shift to this modern approach.
Read Section 3.2, "Developing a New Regulatory Regime," to understand the motivation for the change. Then, review Section 4.3, "Realistic Value of Liabilities," which describes how liabilities are calculated. Notice the emphasis on calculating costs of guarantees and options on a market-consistent basis, often using stochastic models. Finally, read the first three paragraphs of Section 5.1, "The Relevance of Market Consistency," to grasp the core principle of objectivity and transferability.
The reading highlights that market-consistency brings objectivity by anchoring the valuation to market data, reducing the reliance on subjective, discretionary assumptions that characterized older methods. It also supports the crucial regulatory objective of transferability—the idea that the liability value should represent the amount needed to transfer the obligations to another willing party.
A Comparative Framework
We have now covered the main valuation philosophies. The summary table in the ActEd notes provides an excellent high-level comparison.
[PDF] Subject CP1 - CMP Upgrade 2021/22 - Actuarial Education
Now, let's synthesize this information.
Carefully study the summary table in Valuation methods. This is your foundational cheatsheet for comparing the main approaches.
Building on that resource, here is a more detailed framework to help you compare and contrast these key valuation bases for your exam preparation.
| Dimension | Traditional DCF | Statutory (General/Older) | Market-Based (Asset-Led) | Market-Consistent / Realistic |
|---|---|---|---|---|
| Asset Valuation | Discounted value of future income (e.g., dividends). Differs from market value. | Prescribed by rules. Can be book value, market value, or a mix. | Market value. | Market value. |
| Liability Valuation | DCF using a long-term, smoothed discount rate consistent with asset valuation. | Prescribed by rules, often formulaic (e.g., net premium method) with prudent assumptions. | DCF using a discount rate reflecting the expected return on the actual assets held. | DCF of best-estimate cash flows using a market-derived risk-free rate. Includes market value of all options & guarantees. |
| Guiding Principle | Stability and consistency between smoothed asset and liability values. | Compliance with prescribed rules. Often emphasizes prudence. | Consistency between market value of assets and the yield used for liabilities. | Objectivity and transferability. Value is independent of assets held and consistent with market prices. |
| Volatility | Low. Sheltered from market movements. | Varies by rules, but often designed to be stable. | Medium to high. Liability value changes as the asset mix and market yields change. | High. Liability value is sensitive to changes in risk-free rates, which can be volatile (interest rate risk). |
| Typical Purpose | Historical long-term funding valuations for pension schemes. | Regulatory reporting under older regimes. | Internal management metrics; some specific funding valuations. | Modern regulatory reporting (Solvency II), accounting (IFRS 17), economic capital, and M&A. |
This table highlights the fundamental trade-off: traditional and older statutory methods achieve stability by detaching from market realities, while market-consistent methods provide economic realism at the cost of higher volatility in the balance sheet.
Conclusion
In this lesson, we have dissected the main valuation bases used in actuarial practice. We started with the historical traditional discounted cashflow method, which prioritizes stability through smoothed, long-term assumptions. We then contrasted this with statutory bases, which are rule-driven and can vary widely in their proximity to economic reality.
The majority of our focus was on the modern approach of market-consistent valuation, which underpins regulatory regimes like Solvency II. We saw that this approach aims for objectivity and transferability by valuing liabilities in line with market prices, either through a replicating portfolio or, more commonly, by discounting best-estimate cash flows at risk-free rates. This forms the core of a realistic balance sheet, which provides the most economically meaningful view of a firm's obligations.
Your key takeaway is the ability to articulate the trade-offs between these approaches, particularly the tension between the stability of traditional methods and the realism—and associated volatility—of market-consistent valuations.
In our next lesson, we will drill down into the mechanics of calculating these liability values. We will explore the prospective and retrospective methods for calculating technical provisions, which are the practical computational techniques used to arrive at the figures we have discussed conceptually today.
Key Takeaways & Cheatsheet
- Traditional DCF: Values assets and liabilities using consistent, long-term, smoothed assumptions. Benefit: Stable. Drawback: Disconnected from market reality.
- Statutory: A rule-based valuation prescribed by a regulator. Can be traditional, market-consistent, or something else entirely. Its primary purpose is compliance.
- Market-Based (Asset-Led): Values assets at market value and discounts liabilities using the expected return on those specific assets. Drawback: Liability value is not independent of the chosen investment strategy.
- Market-Consistent / Realistic: The modern standard. Aims for an objective value independent of the actual assets held.
- Principle: Value liabilities as if they were traded financial instruments.
- Method: Typically, discount best-estimate cash flows at market-derived risk-free rates.
- Goal: Realism, objectivity, and transferability.
- Trade-off: Introduces market volatility (especially interest rate risk) into the valuation.