Hello! Welcome back.
In our last few lessons, we've systematically built the skills needed to handle a partner's departure. We've covered the revaluation of assets and liabilities, the accounting treatment for goodwill, and most recently, you learned how to calculate a deceased partner's share of profit for the period up to their death.
Today, we'll bring all these pieces together. This lesson will guide you through the process of aggregating all the adjustments to achieve our learning outcome: Calculate the total amount due to the retiring or deceased partner, including capital, goodwill, revaluation, and accumulated profits.
This calculation is the final step before the actual settlement. We'll use the deceased or retiring partner's Capital Account as our primary tool to gather all the amounts they are entitled to receive and subtract any amounts they owe to the firm.
1. What Makes Up the Final Claim?
When a partner retires or passes away, their final claim is not just their capital balance. It's a comprehensive figure that includes their share of everything the partnership has built up over time, adjusted for any withdrawals or losses.
To get a clear overview, please read the following section from your NCERT textbook. It provides a definitive list of the items that are added (credited) and subtracted (debited) to determine the final amount due.
You have learnt that retirement or death of a
This section from your NCERT textbook provides a clear checklist of all the amounts that are included in the final settlement of a retiring or deceased partner.
Please read section 3.1 Ascertaining the Amount Due to Retiring/ Deceased Partner. Focus on the two lists provided: the items included in the sum due (credits) and the potential deductions (debits).
To summarize and visualize the key components that increase the partner's claim, here is a helpful diagram.
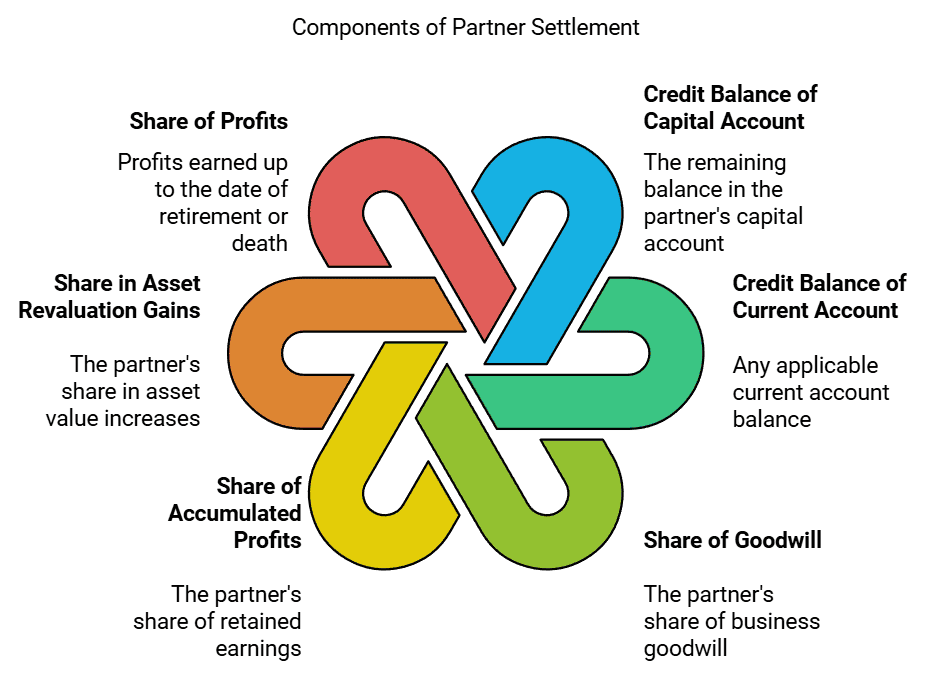
In summary, the calculation involves:
Credits (Amounts to be Added):
- Opening credit balance of their Capital Account (and Current Account, if any).
- Share in accumulated profits like General Reserve and Reserve Fund.
- Share in the profit from the revaluation of assets and liabilities.
- Share of goodwill, compensated by the gaining partners.
- Interest on capital, salary, or commission due up to the date of departure.
- Share of profit up to the date of death (which you learned to calculate in the last lesson, using the P&L Suspense Account).
Debits (Amounts to be Subtracted):
- Drawings made during the year and any interest on those drawings.
- Share in accumulated losses (e.g., a debit balance in the P&L Account or Advertisement Suspense Account).
- Share in the loss from the revaluation of assets and liabilities.
- Share of existing goodwill written off (if it appears in the old Balance Sheet).
Test your understanding!
Let's apply this checklist. Based on the NIOS textbook (LINK), find the total amount due to Munish, a retiring partner, given the following (assume he has a 1/2 share in profits):
- Credit balance in Munish's capital account: ₹20,000.
- Munish’s share of goodwill: ₹7,000.
- General reserve balance shown in the Balance Sheet: ₹10,000.
- Profit on Revaluation of Assets/liabilities: ₹3,000.
- Interest on drawings: ₹1,500.
Calculate the final amount due to Munish.
Show answer
Let's break it down:
- Credit Items:
- Capital Account Balance: ₹20,000
- Share of Goodwill: ₹7,000
- Share of General Reserve (₹10,000 × 1/2): ₹5,000
- Share of Revaluation Profit (₹3,000 × 1/2): ₹1,500
- Debit Item:
- Interest on Drawings: ₹1,500
Calculation:
Total Credits = ₹20,000 + ₹7,000 + ₹5,000 + ₹1,500 = ₹33,500
Total Debits = ₹1,500
Amount Due to Munish = Total Credits - Total Debits = ₹33,500 - ₹1,500 = ₹32,000.
(This matches the answer provided in the NIOS resource LINK, section 6).
2. Preparing the Deceased Partner's Capital Account
The most practical way to perform this calculation is by preparing the Capital Account of the deceased partner. This T-account serves as a worksheet where all credits are posted on the right side and all debits on the left. The final balancing figure is the total amount due.
The following video is an excellent guide. It first explains the format and then walks through two complete problems.
Amount Due to Deceased Partner | Deceased Partners' Capital A/c | Class 12 Accounts Partnership |
This video by CA Hardik Manchanda is a complete walkthrough. It starts by explaining the format of a deceased partner's capital account, then solves two practical problems from T.S. Grewal's textbook, showing exactly how to post each item we've discussed.
Please watch the video from 04:12 to 28:42. 04:12 - 11:16: Pay close attention to the list of items discussed and how they are placed on the credit or debit side of the capital account format. Note the final step: transferring the balance to the 'Executor's Account'. 11:16 - 19:25: Follow the first solved example. It covers capital, interest on capital, drawings, interest on drawings, and interim profit (P&L Suspense). 19:25 - 28:42: The second example is more comprehensive. Observe how existing balance sheet items like General Reserve and Advertisement Suspense are treated, along with a detailed goodwill calculation.
3. Transferring the Final Amount
As you saw in the video, once all adjustments are made, you balance the deceased partner's capital account. This final balance represents the total amount payable by the firm.
This amount is not paid directly from the capital account. Instead, it is transferred to a new account opened in the name of the deceased partner's legal representative, known as the Executor's Account.
The journal entry for this transfer is:
| Date | Particulars | L.F. | Debit (₹) | Credit (₹) |
|---|---|---|---|---|
| Deceased Partner’s Capital A/c Dr. | XXX | |||
| To Deceased Partner’s Executor’s A/c | XXX | |||
| (Being balance in deceased partner's capital account transferred to their executor's account) |
This entry closes the deceased partner's capital account and formally establishes the firm's liability to the executor.
For a brief, clear explanation of how this fits into the Executor's Account, you can watch this short segment.
Death of a Partner | Class 12 | Accountancy | One Shot
This clip from Rajat Arora quickly explains what happens after the capital account balance is determined, showing the journal entry for the transfer to the Executor's account.
Watch from 44:23 to 45:30. This explains how the amount from the capital account (like the ₹6,01,000 calculated in the previous example) becomes the opening balance in the Executor's account.
Conclusion
Fantastic work! You have now connected all the dots in accounting for a partner's departure. By preparing the outgoing partner's Capital Account, you can systematically calculate the final amount due to them or their legal representatives.
Key Takeaways:
- Comprehensive Calculation: The amount due to a deceased partner is the net result of their capital, reserves, goodwill, revaluation gains, and interim profits, less any drawings, losses, or amounts owed to the firm.
- The Capital Account is Key: The deceased partner’s Capital Account is the central ledger used to aggregate all credits and debits to arrive at the final payable amount.
- Final Transfer: The closing balance of the deceased partner's Capital Account is transferred to their Executor’s Account, which then becomes the liability the firm needs to settle.
Preview of the Next Lesson:
Now that we know how much is owed, the next logical question is, how is it paid? In our next lesson, we will focus on recording the settlement of the amount due to an outgoing partner. We will explore scenarios where the payment is made in a lump sum, in installments, or transferred to a loan account. This will involve preparing the Executor's Loan Account.