Recommended resources
The freely available resources this lesson will direct you to.
Hello again. In the previous lesson, you treated a YT purchase as a finite claim on uncertain future income and calculated the realized yield needed to recover its all-in cost. That calculation depends on a crucial distinction: the rate displayed for the underlying asset today is not necessarily the rate that the market has priced into a dated yield token.
This lesson separates those two objects: the underlying asset’s current APY and a yield market’s implied forward rate, usually displayed as implied APY. This distinction is central to explaining Exponent accurately to institutional clients: a YT trade is not simply a purchase of whatever APY happens to be showing on a protocol screen today.
Two rates, two different questions
Consider a yield-bearing asset such as a liquid-staked SOL token, a lending receipt token, or a stablecoin position. It has an underlying APY: the yield it is currently generating, annualized according to the protocol or data provider’s convention.
A dated Exponent market for that asset has an implied APY: the annualized rate embedded in the price at which market participants are trading PT and YT for the period remaining until that market’s maturity.
The rates answer different questions.
| Rate | The question it answers | Time horizon | Who determines it? |
|---|---|---|---|
| Current underlying APY | “What yield is this underlying position generating now?” | Current or recent observation period | The underlying protocol’s economics and reward distribution |
| Implied APY | “What average yield does the market price for the remaining period to maturity?” | From now to a specified maturity date | PT and YT buyers, sellers, LPs, and market makers |
| PT fixed yield at execution | “What return does this PT buyer lock in if held to maturity?” | From trade date to maturity | The executable PT price at that moment |
The underlying APY is a current realized-rate observation. It may be based on a recent rewards distribution, a rolling average, or an instantaneous annualization of a current reward schedule.
The implied APY is a forward-looking market price. It expresses what market participants are collectively willing to pay for the future yield stream over a particular remaining term.
Exponent’s documentation puts the distinction plainly: implied APY is a market projection of future yield and need not match the underlying product’s current or historical performance.
Chapter 3: What is Yield Token (YT)
Watch Pendle’s “Chapter 3: What is Yield Token (YT)” for a compact visual example of an asset with one current underlying APY and a different YT implied APY. The terminology transfers directly to Exponent’s PT/YT markets.
Watch the stETH example. Focus on why the 3.7\% current underlying APY and the 3.5\% implied APY are not contradictory: one is a current yield observation, while the other is the market valuation of future yield.
Implied APY is a maturity-specific forward view
An Exponent yield market is defined by both an underlying asset and a maturity. A YT-JitoSOL market maturing in 90 days does not price “JitoSOL yield forever.” It prices the right to the yield generated between now and that 90-day maturity.
Let:
- be the annualized yield generated by the underlying asset through time;
- be the remaining term, measured in years;
- be the underlying APY observed today;
- be the implied APY quoted by the dated yield market.
Conceptually:
The relevant realized yield outcome for a maturity-held YT is closer to the average future yield over the remaining term:
The implied APY is the market’s current pricing of that uncertain future outcome. In a simplified framing, a YT buyer’s thesis is:
But this should not be read as a mechanical arbitrage rule. Actual YT profitability also depends on execution costs, incentive treatment, asset denomination, and the market’s risk premium.
Read Exponent Finance’s explanation of underlying versus implied APY. It is particularly useful because it links the rate distinction to the economic choice between owning fixed principal exposure and variable yield exposure.
In the discussion that begins “The Implied APY does not follow exactly the underlying APY,” read the forward-looking distinction. Then, in the “Underlying APY” explanation, read the definition of underlying APY. Continue into the “Implied APY” explanation and read how market pricing differs. Focus on the role of expected future average yield and risk premium, rather than treating implied APY as a protocol forecast.
A useful way to state the distinction in a client conversation is:
The current underlying APY tells us what the asset is earning today. The implied APY tells us what the yield market prices for the average yield from today until this specific maturity. The spread between them is a market view and a risk premium, not a guaranteed return.
Why the two rates can differ
Suppose a 90-day USDC lending position has a displayed current APY of , while its 90-day Exponent yield market trades at an implied APY of .
Those figures can coexist perfectly rationally.
If the current yield persisted unchanged for the full 90 days, then one million USDC of represented principal would earn approximately:
At a simplified implied rate, the market is pricing a yield outcome closer to:
The difference is not “free yield.” It reflects uncertainty about what happens during the next 90 days.
Several conditions could justify the market pricing a lower implied rate than today’s displayed underlying APY:
- The APY includes temporary reward emissions that may end.
- Lending utilization may decline, reducing borrowers’ interest payments.
- The displayed APY may be a short rolling observation following an unusual rate spike.
- PT demand may be strong because allocators value a known maturity payout.
- YT buyers may require compensation for smart-contract, underlying-protocol, liquidity, or incentive-token risks.
- Market participants may simply disagree about the forward yield path.
Conversely, implied APY can exceed current underlying APY when the market expects a yield recovery or additional rewards. For example, current staking yield might look temporarily weak because of short-term validator dynamics, while buyers expect the average yield to be higher over the remaining term. Markets may also price in prospective points, airdrops, or incentive distributions when these accrue to YT holders.
The key point is that the market is pricing the future average, not copying the dashboard’s current annualized number.
A rate spread is a thesis, not an arbitrage
The following three statements are materially different:
- “The underlying asset currently yields .”
- “The 120-day yield market implies .”
- “A YT buyer will earn .”
Only the first is an observation about the present. The second is an executable, maturity-specific market quote. The third is unsupported unless the asset continues to generate the same yield and all other assumptions hold.
For a YT buyer, a positive spread between current APY and implied APY creates a potential opportunity:
However, the economically relevant comparison is:
The YT buyer benefits if the yield realized over the whole remaining period exceeds the yield priced at entry, after costs and any relevant incentive assumptions. The current APY is evidence that may inform that view, but it is not proof.
For a PT buyer, the interpretation is different. The PT price translates into a return that can be locked in at entry and earned if PT is held to maturity. That fixed return is known at execution; the underlying APY can subsequently rise or fall without changing the PT’s maturity redemption amount.
This creates the basic market transfer:
- PT holders give up uncertain future variable yield in exchange for a known maturity return.
- YT holders take exposure to whether future realized yield exceeds the rate priced by the market.
- Liquidity providers and market makers facilitate that transfer while taking inventory, execution, and active-management risk.
Why “forward rate” needs careful institutional language
In conventional fixed income, a forward rate can refer to a rate derived from a curve through a relatively formal no-arbitrage relationship. Exponent’s implied APY is similar in one important respect: it is a market-derived, forward-looking rate for a defined future period.
The analogy stops there.
Exponent’s implied APY should not be presented as a pure, risk-free forward rate. Its level can reflect:
- expected organic yield from the underlying asset;
- expected incentive or points value, if relevant to the market;
- smart-contract and operational risks;
- underlying protocol or validator risks;
- liquidity conditions and exit costs;
- demand for fixed-rate PT exposure;
- supply and demand for YT exposure.
Thus, a more accurate institutional description is:
Exponent’s implied APY is the annualized, market-priced rate for the remaining yield period of a specified asset and maturity. It is a forward-looking consensus price that can include risk and liquidity premia; it is not a guarantee or a direct forecast issued by the underlying protocol.
That language avoids two common errors: treating the quote as a promised yield and treating a rate spread as a riskless trade.
Reading an Exponent market screen correctly
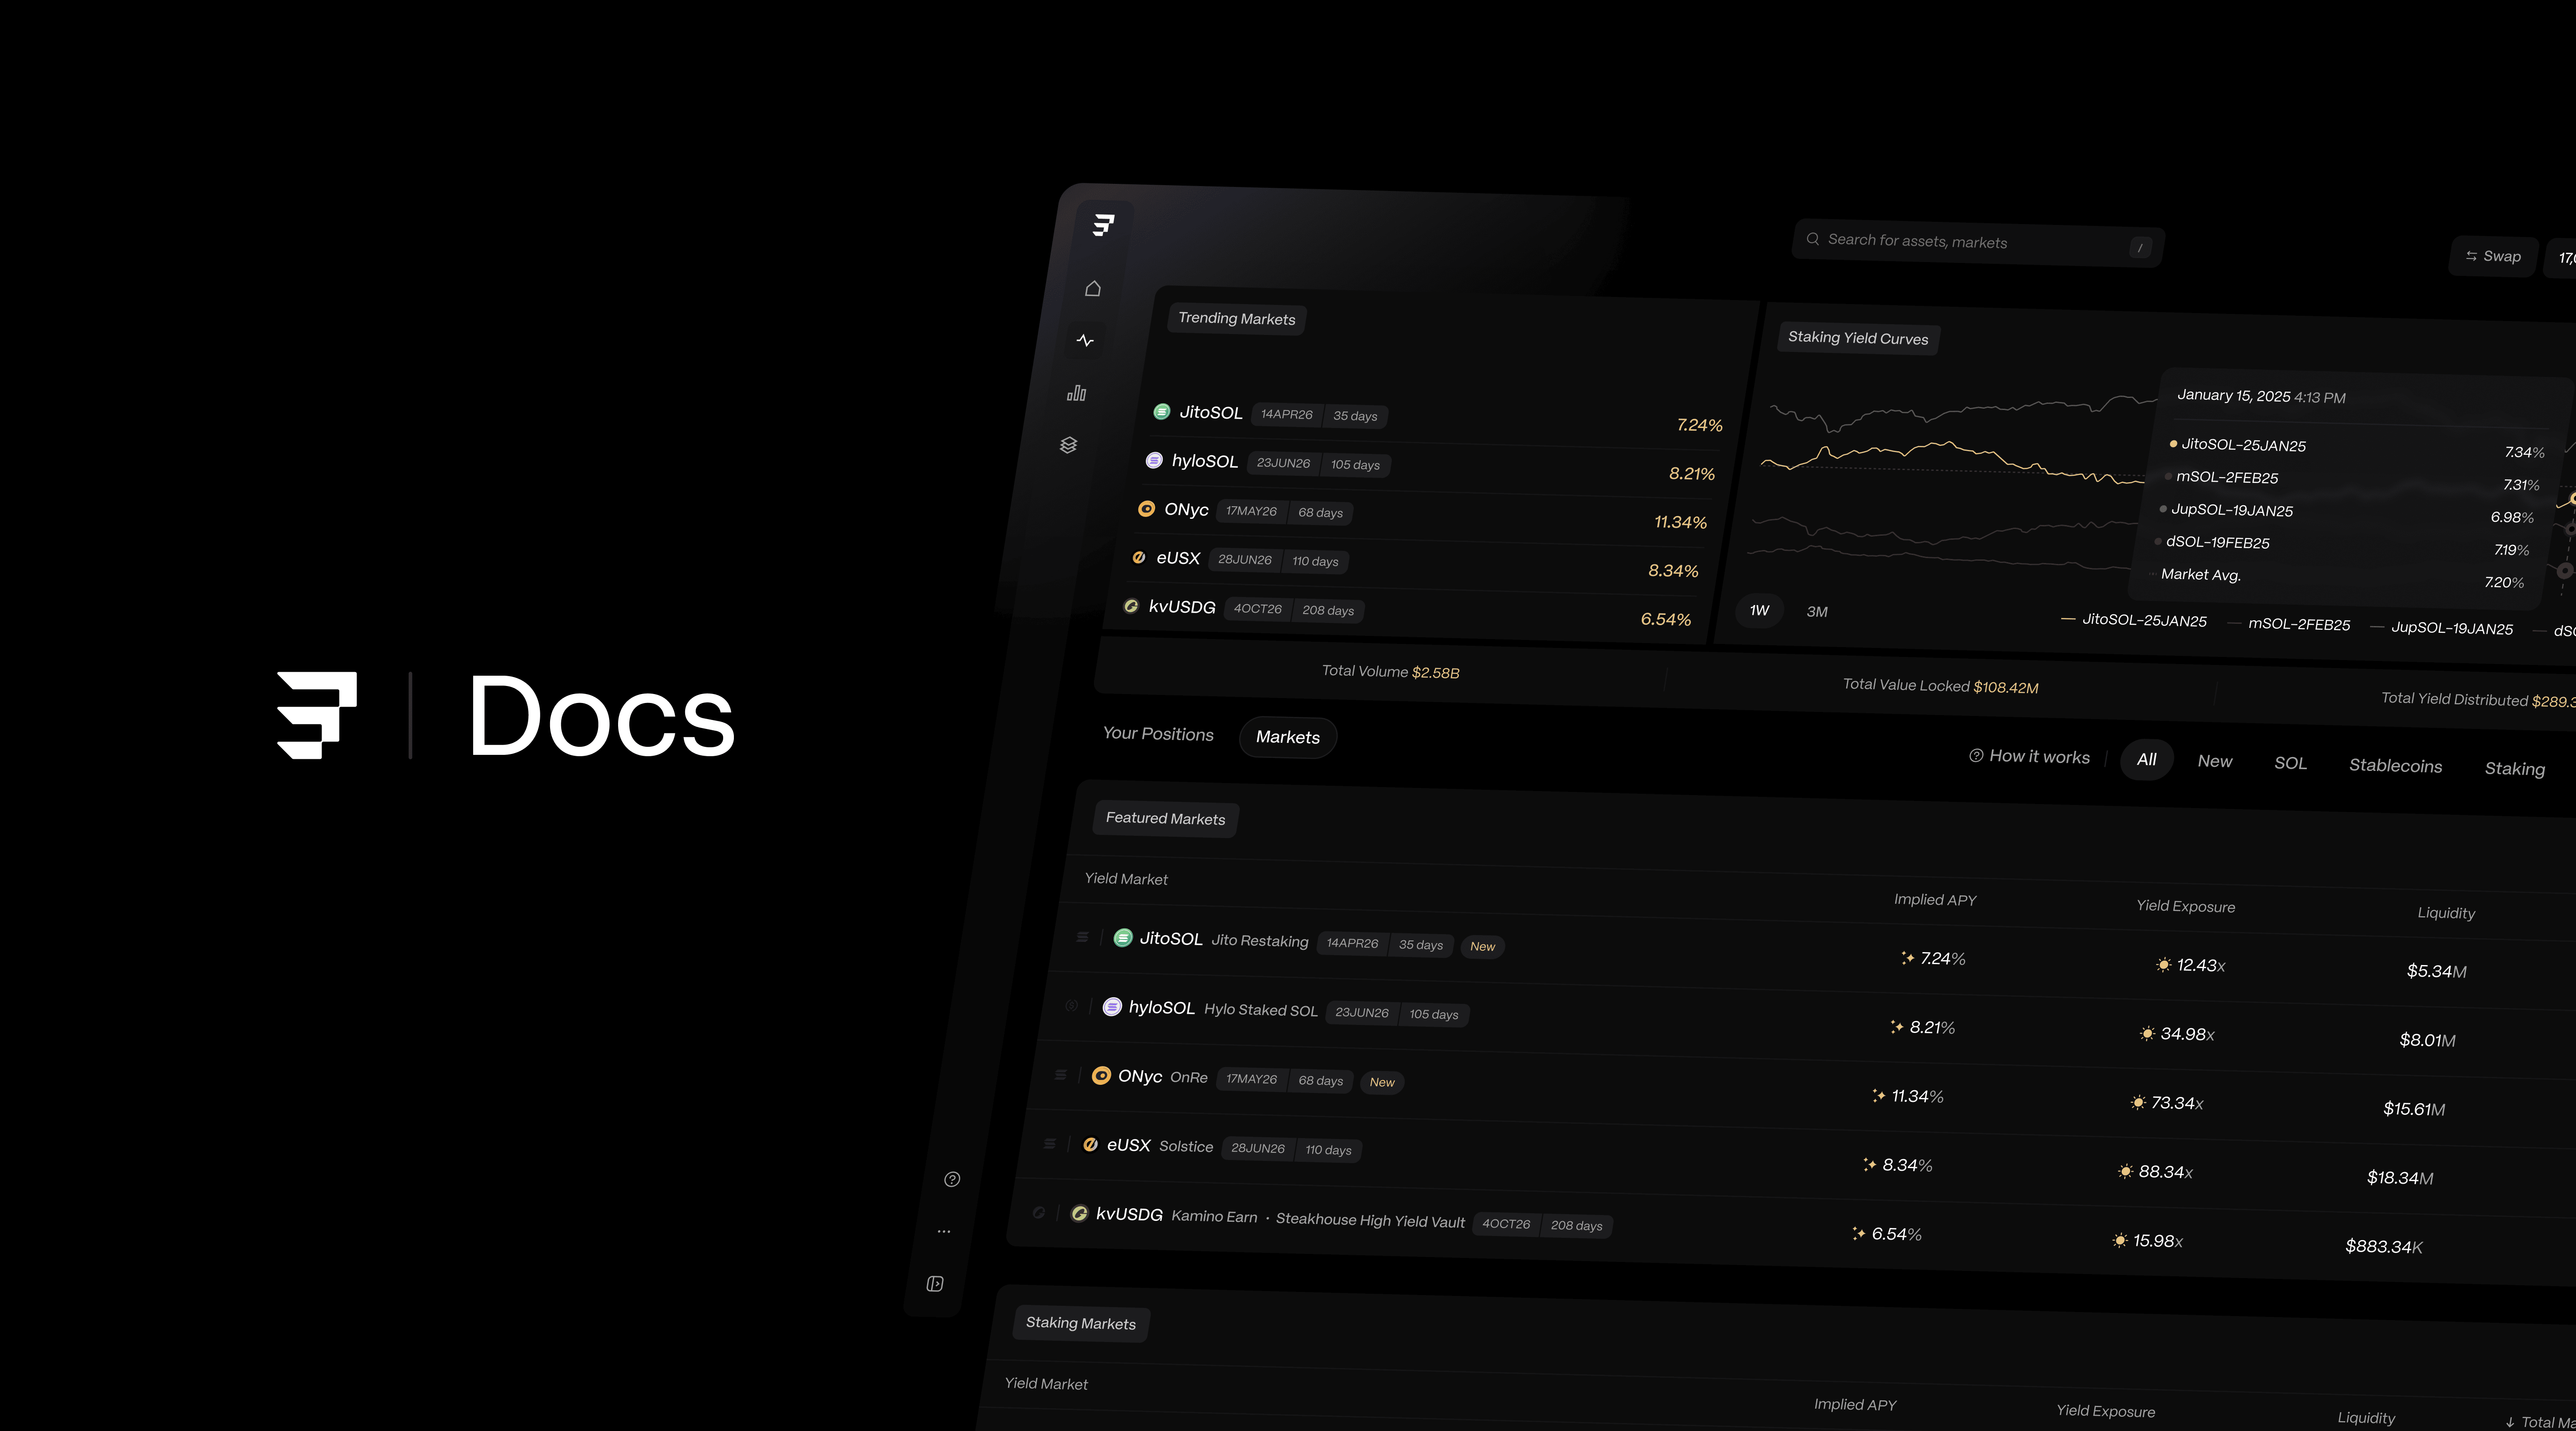
When reviewing a yield-market screen, establish the following before drawing a conclusion:
| Check | Why it matters |
|---|---|
| Underlying asset | Determines the economic source of yield: staking, lending, LP fees, incentives, or another strategy. |
| Maturity date | Defines the exact forward period that the implied rate covers. |
| Current underlying APY methodology | A current APY may be trailing, instantaneous, net of fees, or inclusive of incentives. |
| Implied APY convention | Confirm day count, compounding convention, and whether displayed numbers are gross or net of fees. |
| Trade size and executable level | A displayed mid-price may not be achievable for an institutional ticket. |
| Yield composition | Separate organic yield from emissions, points, and volatile-token rewards. |
| Risks priced into the spread | A lower implied rate may compensate YT buyers for risks rather than signal a simple mispricing. |
A disciplined desk note might say:
“The underlying currently displays a annualized yield, based on its recent reward distribution. The 61-day market implies at the quoted executable size. Our base case is a realized average yield, with downside to if incentives decline. The apparent current-versus-implied spread is not treated as arbitrage because the market includes liquidity, protocol, and reward-schedule uncertainty.”
This separates observations, pricing, and the analyst’s own assumptions.
Common communication mistakes
“The underlying is paying 9%, so the YT will earn 9%.”
Incorrect. The YT earns the yield actually generated from now through maturity. The current rate may rise, fall, or be based on a methodology that differs from the market quote.
“Implied APY is Exponent’s forecast.”
Incorrect. It is market-driven. Exponent provides the venue; participants determine the price through PT and YT trading.
“A lower implied APY than current APY is an arbitrage.”
Usually incorrect. The spread may reflect a realistic expectation of declining yield, risk compensation, incentives that will expire, or liquidity and execution frictions.
“PT’s fixed APY and YT’s implied APY are interchangeable labels.”
Incorrect. A PT buyer locks an executable maturity return at entry. A YT buyer pays a market-implied cost for uncertain future yield. They are complementary exposures, but their payoff profiles differ.
“The implied APY applies indefinitely.”
Incorrect. It applies to the remaining life of one specified market. As maturity approaches, the period being priced becomes shorter and YT time value decays.
Key takeaways
The underlying APY is the current or recently observed yield generated by the underlying asset. It is variable and can change as staking rewards, borrowing demand, incentives, validator performance, or protocol conditions change.
The implied APY is the yield market’s annualized, forward-looking price for the average yield expected from today until a specified maturity. It is market-driven and can include risk, liquidity, and supply-demand premia.
The central comparison is not:
It is:
A current APY above implied APY may support a YT thesis, but it does not establish a guaranteed return. For institutional analysis, always state the maturity, quote convention, execution size, yield composition, and risks embedded in the apparent spread.
Next, you will examine how a change in implied rates affects a PT holder differently depending on whether they exit before maturity or hold through redemption.