Recommended resources
The freely available resources this lesson will direct you to.
Hello again. Previously, you separated an underlying asset’s current APY from the market’s implied APY for a particular maturity. That distinction now becomes a mark-to-market question: a PT locks its maturity payoff when bought, but its sale price before maturity continues to respond to changes in the market-implied rate.
This lesson develops the practical rule for PT holders:
- If you sell before maturity, a fall in implied rates generally raises PT’s price, while a rise generally lowers it.
- If you hold to maturity, rate moves affect interim mark-to-market value and opportunity cost, but not the contracted redemption amount of one PT.
We will use a simplified short-dated PT example, then translate it into institutional language appropriate for a client considering fixed on-chain yield.
The same PT has two economically different horizons
A principal token is a dated claim on one unit of the designated underlying asset at maturity. If its price is below one unit of that asset today, the discount is the fixed return available to a buyer who holds through redemption.
For clarity, measure prices in units of the underlying yield asset:
- Buy PT today for units of underlying.
- At maturity, redeem PT for unit of underlying, subject to the protocol and underlying asset functioning as intended.
- The difference between and is the maturity return.
This produces two distinct holding-period experiences.
| Holding decision | What determines the outcome? | Exposure to implied-rate moves |
|---|---|---|
| Sell PT before maturity | The executable PT market price when exiting | Direct exposure |
| Hold PT to maturity | The predetermined redemption of underlying per PT | No terminal-price exposure; interim mark-to-market still changes |
The word fixed applies to the return relative to the underlying asset if the PT is held to maturity. It does not mean the PT has a fixed secondary-market price every day.
Read Exponent’s “Yield Markets” documentation for its official treatment of PT returns, early-exit market risk, and maturity redemption.
In the “Understanding Risks and Returns” section, begin with the PT-risk bullet and read the risk discussion. Then continue to the “PT Returns” material, especially the PT-return explanation. Focus on the distinction between the locked maturity return and the uncertain proceeds from an early sale.
Why implied rate and PT price move in opposite directions
A PT behaves economically like a short-dated zero-coupon claim denominated in the underlying asset. Its price is the present value of its fixed maturity redemption.
Using a simplified simple-interest convention with an ACT/365 day count:
where:
- is the PT price in units of the underlying asset;
- is the market-implied annualized rate for the remaining term;
- is time remaining to maturity in years.
The formula makes the direction intuitive:
- A lower implied rate means the discount to maturity is smaller, so the PT price is higher.
- A higher implied rate means the discount is larger, so the PT price is lower.
On Exponent, buying PT represents demand for fixed-rate exposure. That demand tends to bid up PT’s price and correspondingly reduce the displayed implied rate. Buying YT has the opposite directional effect: it reflects demand for variable-yield exposure and tends to increase implied rates.
This relationship concerns the rate priced by the yield market, not necessarily the underlying protocol’s current APY. Implied rates can move because of expectations for future yield, changes in risk appetite, liquidity conditions, or demand for fixed-rate positions, even if the underlying dashboard APY has barely moved.
Yield Stripping & Swap - Exponent Docs
Use Exponent’s “Yield Stripping & Swap” documentation to connect PT and YT order flow with the market’s implied-rate quote.
In the “Implied Rate” subsection, read the implied-rate explanation. Pay particular attention to the table showing why PT buying lowers the implied rate and YT buying raises it. Treat this as the market’s pricing convention and directional mechanism, not as a forecast guaranteed by Exponent.
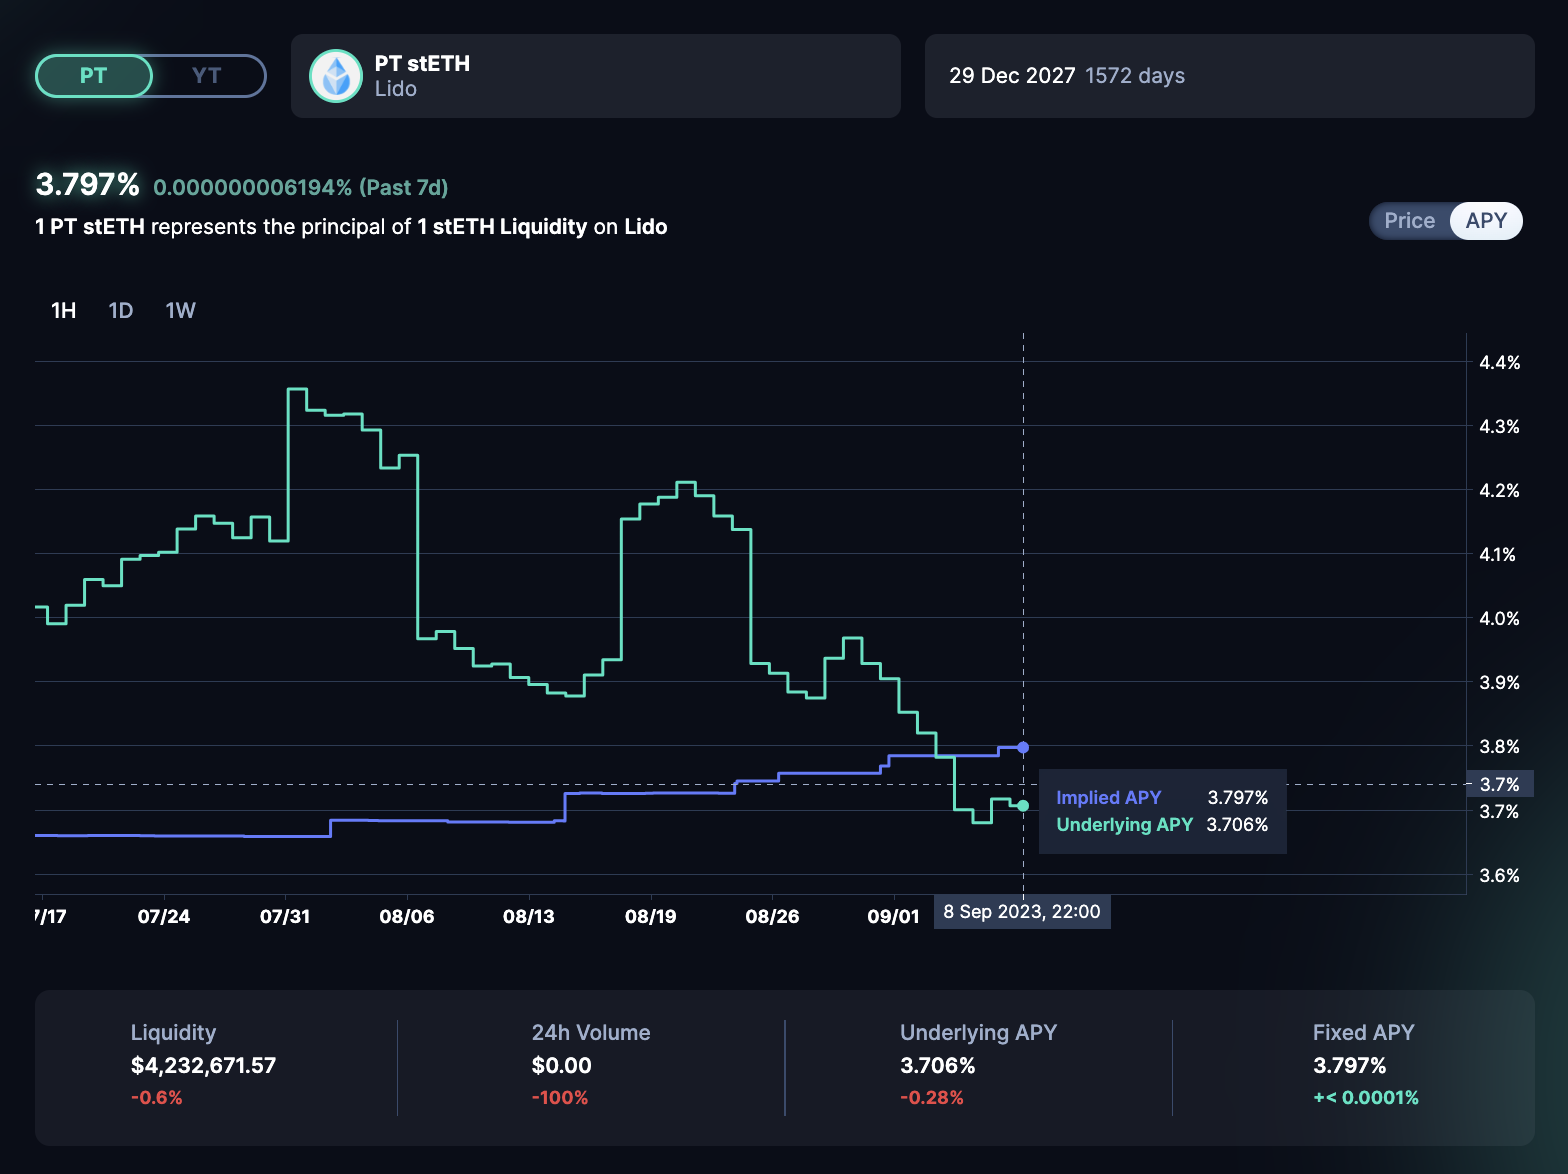
The chart is useful for spotting the distinction between rates, but it is not enough to calculate a PT investor’s PnL. For that, a desk needs the actual PT entry price, the executable exit price, remaining maturity, trade size, and execution costs.
Worked example: exiting before maturity
Assume an institution buys PT units with 90 days remaining. The PT trades at an implied annual rate. We use simple interest and an ACT/365 convention solely for illustration.
At entry:
The institution pays approximately units of the underlying asset for PT. If held until maturity, the PT redeem for underlying units.
Now suppose 30 days pass. There are 60 days remaining.
Case 1: implied rate is unchanged
If the market still implies , the PT price has nevertheless risen because there is less time left for the original discount to remain:
The early-sale gain per PT is:
This is carry and pull-to-par. Time has passed, so a claim that redeems at naturally converges toward , all else equal.
Case 2: implied rate falls to
Suppose demand for fixed yield increases, or market participants become less optimistic about future variable yield. The implied rate falls to :
The early-sale gain per PT is now:
The holder benefits from both:
- Time passing, which pulls the price toward par.
- The implied-rate decline, which further raises the market value of PT.
For PT, the gross mark-to-market gain is approximately underlying units, before spread, slippage, protocol fees, and any costs of converting the proceeds.
Case 3: implied rate rises to
Now assume future-yield expectations increase materially, YT demand rises, or market participants require a larger return to own PT. The implied rate rises to :
The early-sale loss per PT is:
Even though 30 days of convergence has helped the holder, the adverse rate move is large enough to produce a loss on an early sale.
The key lesson is not merely “rate rises hurt PT.” Time-to-maturity matters. A PT price is pulled upward toward its maturity redemption every day, while implied-rate changes can move it in either direction.
The holder who stays until maturity
Return to the same entry point: the institution purchased PT at and is entitled to redeem underlying unit per PT at maturity.
If it holds all PT until maturity, the redemption amount is:
That redemption does not depend on whether the implied rate subsequently trades at , , or .
Its maturity return in underlying units is:
Over the original 90-day holding period, that corresponds to the assumed simple annualized fixed rate.
The holder may see interim unrealized gains or losses if the PT is marked to market, but these do not alter the scheduled one-for-one redemption. The distinction is identical in spirit to a conventional fixed-income position:
- A price-sensitive portfolio reports mark-to-market movements before maturity.
- A holder able and willing to retain a valid claim until redemption receives the specified maturity payment.
However, the analogy has limits. A PT is not a risk-free government bill. “Holding to maturity” eliminates the need to sell a price-sensitive PT position, but it does not eliminate:
- smart-contract and protocol risk;
- risks in the underlying yield asset and its dependencies;
- depeg or asset-price risk when evaluating returns in USDC or fiat;
- custody, wallet, settlement, and operational risks;
- the opportunity cost of having locked a fixed return if variable yields subsequently rise.
The fixed return is therefore best described as deterministic conditional on successful redemption and measured in the underlying asset, not as risk-free in an institutional sense.
Chapter 2: What is Principle Token (PT)
Watch Pendle’s “Chapter 2: What is Principle Token (PT)” for a compact visual explanation of PT discount, fixed yield, and early-sale price appreciation. Its mechanics are broadly applicable to fixed-maturity yield-token markets; use Exponent’s own documentation for protocol-specific features.
Watch PT mechanics to review why a PT bought at a discount can provide a locked maturity return. Then watch early exit for the relationship between stronger PT demand, a lower locked rate, a higher PT price, and an early-sale gain. Keep the critical qualification in mind: a favorable displayed price must be executable at the institution’s intended size.
A compact comparison for client conversations
| Question | Sell before maturity | Hold to maturity |
|---|---|---|
| Does a fall in implied rates matter? | Yes. PT price generally rises, creating a potential capital gain. | Not to the redemption amount. It may create an unrealized gain or an opportunity to monetize early. |
| Does a rise in implied rates matter? | Yes. PT price generally falls, potentially causing a realized loss if sold. | Not to the redemption amount, though the holder has locked a rate that may now be unattractive. |
| Is the original fixed return fully earned? | Not necessarily. The realized return is determined by the exit price and costs. | Yes, in underlying-asset terms, assuming redemption succeeds. |
| Is liquidity relevant? | Very. Bid-ask spread, market depth, slippage, and routing affect exit proceeds. | Less relevant for redemption itself, but relevant if the institution later needs to change course. |
| Main economic risk | Mark-to-market rate risk plus execution risk. | Opportunity cost plus protocol, underlying-asset, and operational risk. |
For an Institutional Sales Lead conversation, the most precise short explanation is:
A PT buyer locks a maturity return at the entry price. If the institution needs liquidity before maturity, the PT becomes a rate-sensitive asset: falling implied rates tend to increase its sale value and rising implied rates tend to reduce it. If the institution holds until maturity, interim implied-rate moves do not change the one-for-one redemption in the underlying asset, although all protocol, asset, and operational risks remain.
Rate sensitivity declines as maturity approaches
A 180-day PT generally reacts more to a given rate move than a 14-day PT, because more of its value is still tied to the market’s discount rate. As maturity approaches, the remaining discount shrinks and the PT converges toward par.
For small changes in the simplified model, rate sensitivity can be approximated as:
The term
acts like a modified-duration measure under this simplified setup. The negative sign captures the inverse relationship: a higher implied rate lowers PT price.
This is useful for risk framing, but it is only an approximation. Actual realized exit PnL can differ because Exponent markets have discrete liquidity, spreads, varying trade sizes, order-book versus CLMM execution, fees, and potentially different annualization conventions from the simple formula used here.
A professional PT trade ticket should therefore record:
- entry PT price and executable implied rate;
- maturity date and day-count convention;
- position size and denomination;
- expected holding horizon;
- exit venue and estimated liquidity;
- sensitivity to plausible implied-rate shocks;
- the separate fiat or stablecoin price risk of the underlying asset.
Key takeaways
A PT is a claim that redeems for one unit of the designated underlying asset at maturity. The buyer’s fixed return arises because the PT is acquired at a discount.
For an early seller, PT is rate-sensitive:
- implied rate down generally means PT price up;
- implied rate up generally means PT price down;
- time passing independently contributes pull-to-par;
- actual exit PnL must include executable price, spread, slippage, and fees.
For a maturity holder, implied-rate changes do not alter the predetermined PT redemption amount. They affect interim mark-to-market value and opportunity cost, not the contractual maturity payoff in underlying units.
Next, the course moves from the holder’s payoff to the transaction plumbing: tracing a PT or YT trade through stripping, merging, flash swaps, and PT liquidity.